
Understanding crypto volatility shapes how investors prepare for risk, allocate capital, and respond to sudden moves. Crypto markets still show larger, faster swings than most traditional assets, and those swings cluster around cycle turning points. This guide gives a compact, practical view for 2026: what volatility means for a portfolio, the signals that precede cycle shifts, concrete phase recognition cues, and clear rules for position sizing and risk. Readers will find specific numbers, honest trade-offs, and links to deeper MoneySideOfLife resources to help turn theory into repeatable practice.
Key Takeaways
- Crypto volatility, characterized by large and rapid price swings, significantly impacts portfolio risk and dictates the need for precise position sizing.
- Volatility spikes commonly signal market cycle turning points, with bear, recovery, bull, and late-cycle phases each showing distinct volatility and volume patterns.
- Investors should anchor position size to realized volatility, halving exposure when volatility doubles to maintain consistent risk per trade.
- Monitoring multiple indicators like macro liquidity, on-chain activity, and derivatives funding rates can help anticipate shifts in volatility regimes and market cycles.
- Effective risk management includes limiting leverage to 2x, capping individual positions at 5–10% during high volatility, and maintaining a 10–20% cash or stablecoin buffer for flexibility.
- Applying volatility-adjusted rules and recognizing accumulation signals enables disciplined decision-making and capital preservation amid crypto market fluctuations.
What Is Crypto Volatility And Why It Matters To Your Portfolio
Fact first: crypto volatility is the size and speed of price moves: Bitcoin and major altcoins can swing 5–15% in a single day during stressed periods. That level of movement raises drawdown risk and can erase months of returns in days. Volatility matters because it defines dollar risk, the higher the volatility, the smaller a position must be to keep a fixed percentage risk per trade.
Concrete example: if an investor targets 1% risk per trade and Bitcoin’s 14-day ATR indicates 8% typical moves, a $100,000 portfolio should size a position so a stop loss equals $1,000: with volatility doubling, the position must halve. This math prevents forced liquidations and preserves optionality. Volatility also affects taxes, margin costs, and emotional stamina, sudden 30% swings trigger behavior that often worsens outcomes.
A practical metric to watch is realized volatility (daily returns standard deviation) and implied volatility on derivatives markets when available. High realized volatility with thin exchange liquidity increases execution slippage and liquidation cascades. For a primer on core crypto risks and market context, see the site’s compact crypto primer.
How Volatility Interacts With Market Cycles — Key Drivers And Signals
Answer up front: volatility spikes at turning points and during speculative blow-offs: troughs often show muted realized volatility. That relationship helps time risk exposure.
Volatility rises when liquidity tightens or leverage is concentrated. In 2022–2023, sharply negative liquidity conditions coincided with high realized volatility and forced deleveraging across spot and derivatives. Similarly, late-cycle speculation creates “blow-off tops” with extreme intraday ranges and expanding market breadth. Conversely, cycle troughs often display narrow ranges as weak hands have exited and volatility base stabilizes.
Investors should watch drivers that change volatility regimes: central bank policy and macro liquidity, network-level activity, exchange order-book depth, and leverage on major derivatives platforms. When multiple drivers align, for example, tightening liquidity plus rising derivatives funding rates, volatility risk increases faster than any single indicator suggests. These compound signals help avoid being overly exposed heading into a fragile regime.
Practical Market Cycle Phases And How To Recognize Them
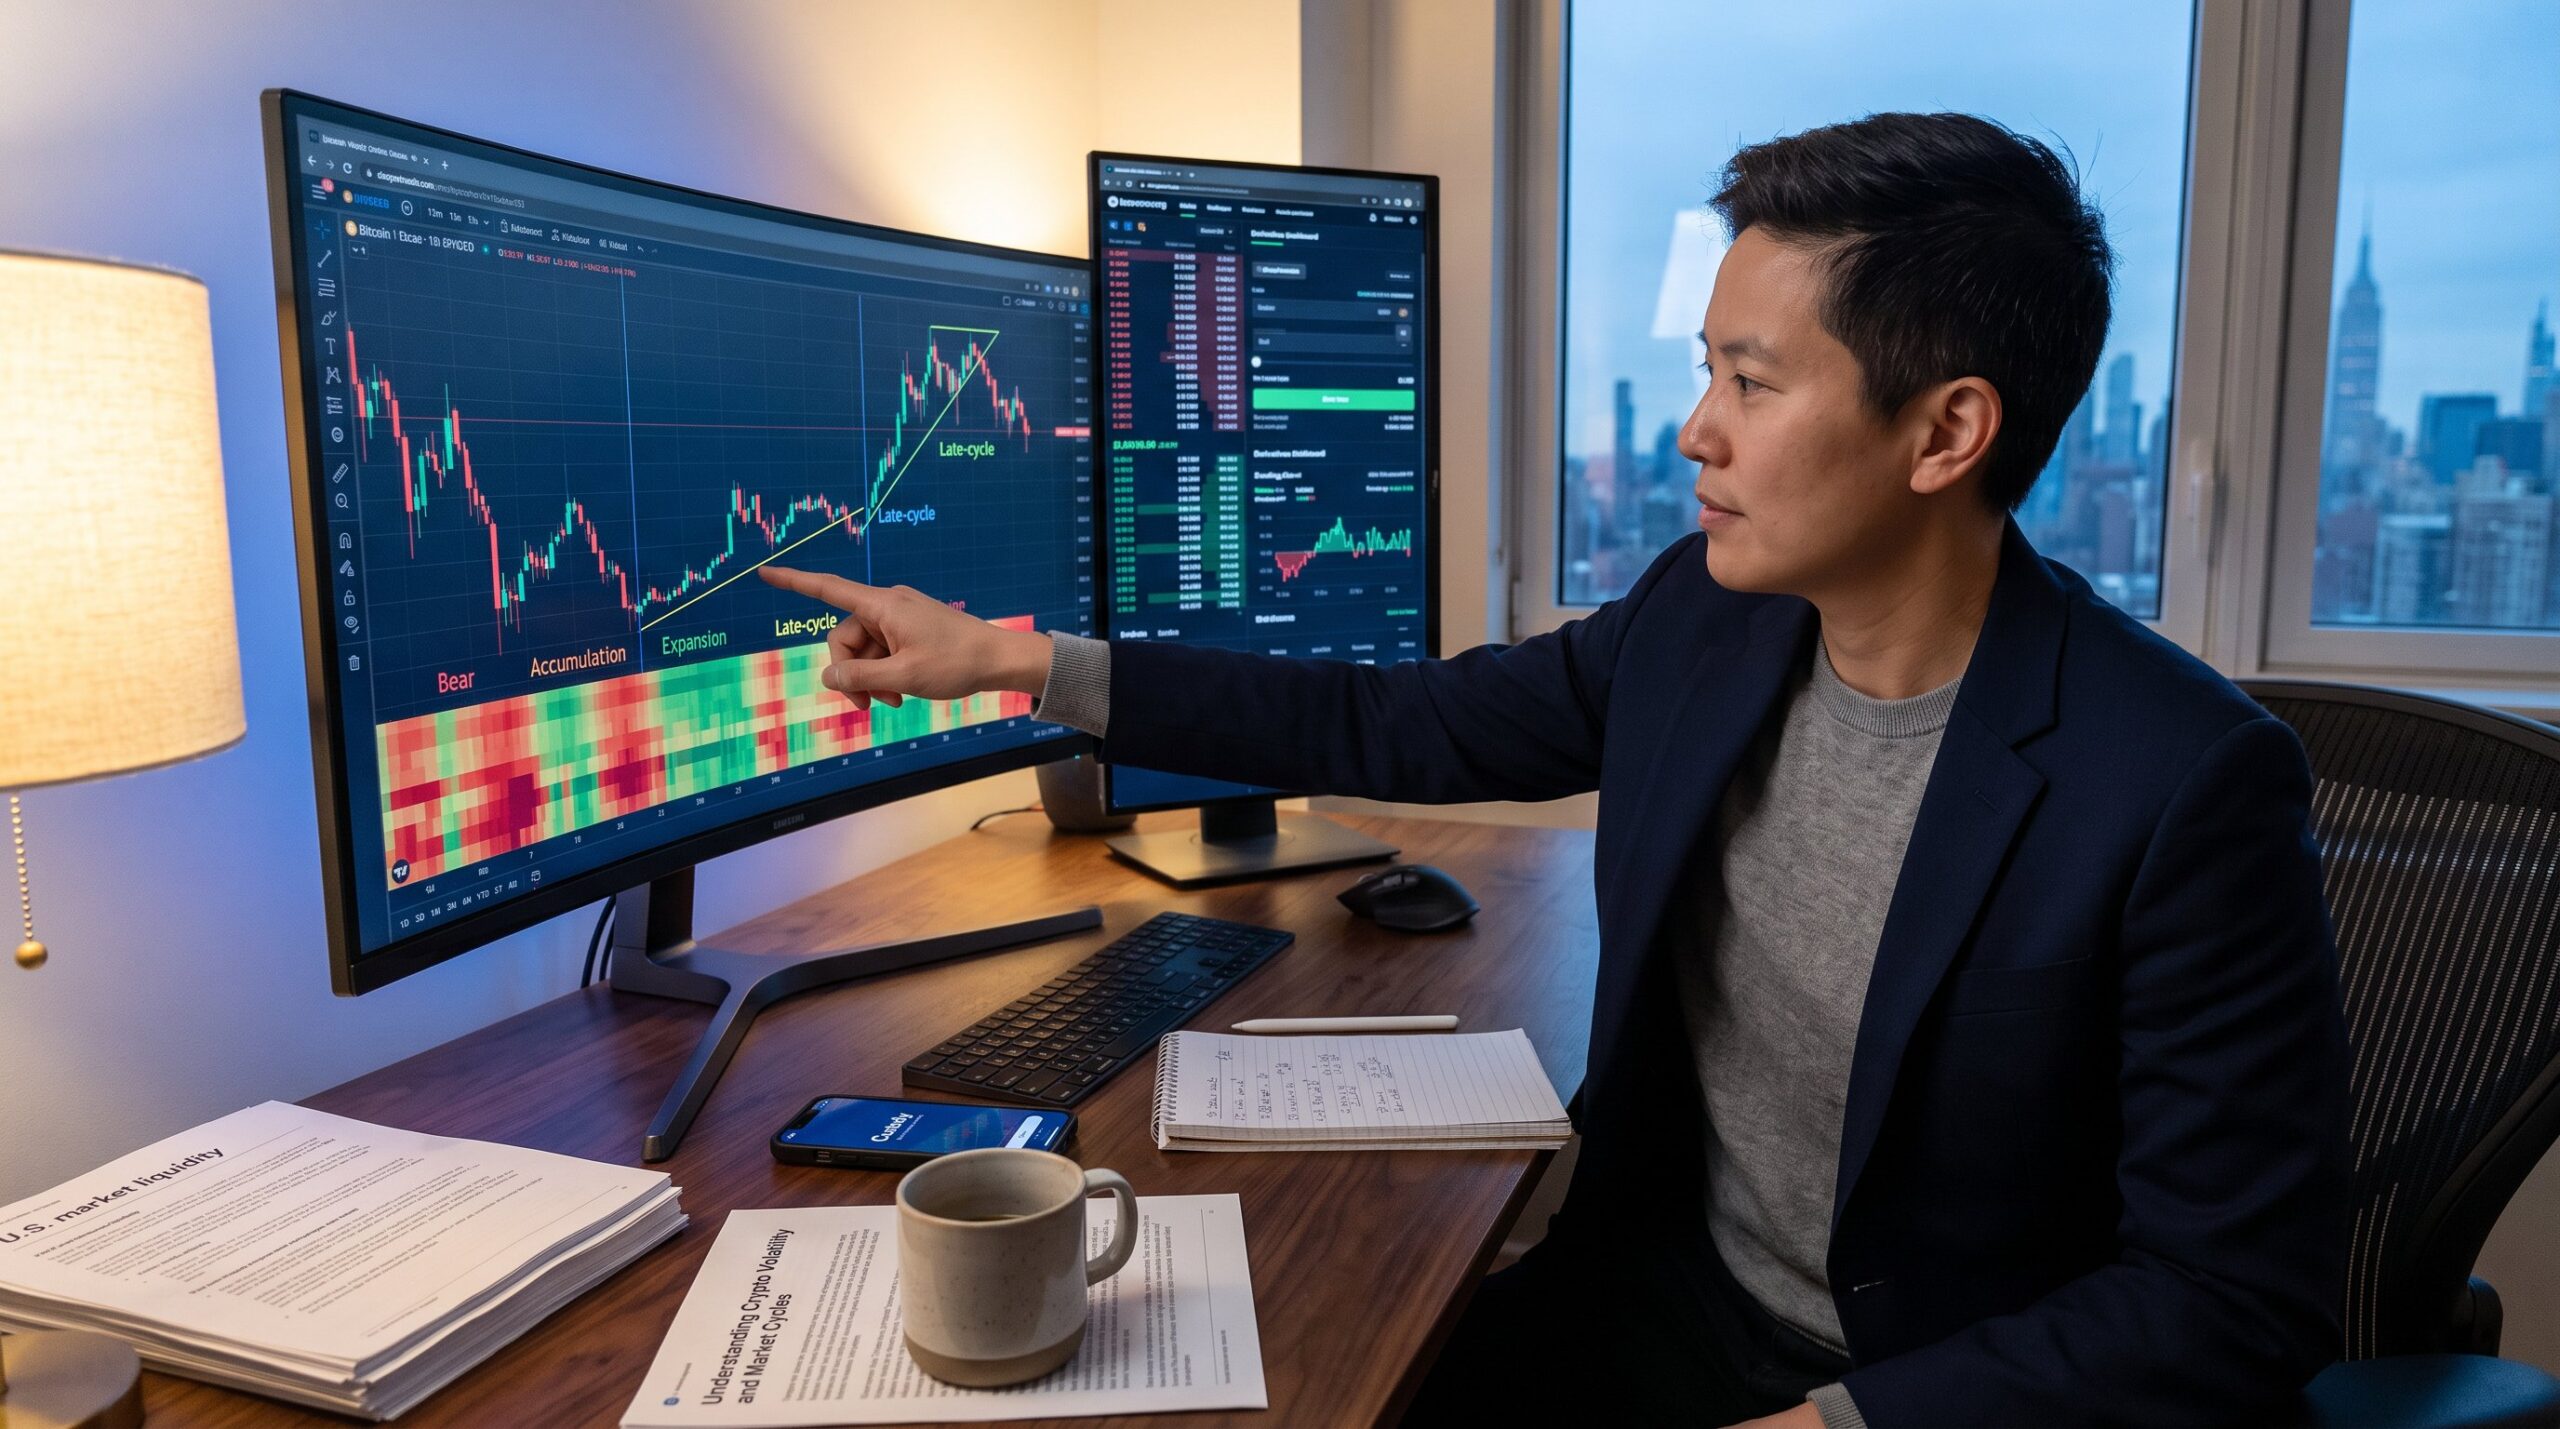
Direct answer: cycles commonly follow four phases, bear, recovery/accumulation, expansion/bull, and late-cycle, each with measurable cues.
Bear market (signal): sustained decline, often defined by a 20%+ drop from recent highs. Expect falling volumes, rising on‑chain outflows, and persistent negative sentiment. Example: during bear phases, weekly trading volume can fall 30–60% from peak levels, and exchange reserves often rise as sellers exit.
Recovery/accumulation (signal): price stabilizes, volatility often compresses, and long-term holders begin incremental buys. Look for a slowdown in weekly realized volatility, rising spot flows into exchange-tracked ETFs or custody, and steady growth in network activity.
Expansion/bull market (signal): rising prices, expanding participation, and increased retail search interest. Realized volatility often increases but remains correlated with positive price trend: speculative altcoins lead breadth expansion.
Late-cycle (signal): rising prices with weakening liquidity, elevated leverage, and diverging fundamentals. Watch for shrinking order-book depth, large funding rate spikes, and rising concentration in a few large-cap assets. These are classic warning signs of a top.
Investors who map these signals to simple rules, reduce size on late-cycle liquidity deterioration, add on clear accumulation signals, move from reactive trading to structured decision-making.
Actionable Strategies For Investors: Risk Management, Position Sizing, And Timing
Core answer: anchor position sizing to volatility, cap concentration, avoid high leverage, and use layered stops tied to ATR or volatility bands. Those looking for more depth can read the risks guide.
Position sizing rule: target 1% portfolio risk per position as a default. When realized volatility doubles, halve position size. For example, with a $200,000 account and 1% risk target ($2,000), if ATR-implied stop distance is 10%, the tradable position equals $20,000. If volatility jumps to 20%, position drops to $10,000.
Stops and timing: use ATR-based stops and widen stops in low-liquidity contexts to avoid being stopped by noise. Consider scaling entries, build positions across lower-volatility days during accumulation and trim into late-cycle spikes.
Leverage and concentration: avoid more than 2x portfolio leverage and cap single-position exposure at 5–10% during high volatility regimes. Historical data shows concentrated, leveraged bets account for a disproportionate share of forced liquidations.
Portfolio-level controls: maintain a volatility buffer (cash or stablecoin) equal to 10–20% of the portfolio to rebalance into dislocations. Use sentiment and on‑chain signals together to time re-entry rather than relying on price alone. For practical wallet and custody choices tied to execution risk, see the site’s wallets guide. For phase tactics and timing techniques, a clear external primer outlines methods to take advantage of cycle phases in practice cycle primer.
Conclusion
Takeaway: volatility is a feature, not a flaw, it shapes position sizing, timing, and risk rules. By watching macro liquidity, on‑chain activity, market structure, and sentiment together, investors can recognize cycle phases and act with discipline. Small, consistent rules, volatility-adjusted sizing, capped concentration, and a readiness to add at validated accumulation signals, preserve capital and create options when markets pivot.