
Crypto payments for small businesses can offer another route for collecting customer funds, particularly when you sell across borders or serve customers who prefer digital assets. The commercial case depends on more than the advertised transaction rate: processing charges, settlement choices, price volatility, tax treatment, security controls and reconciliation all affect the outcome. For a finance leader, the question is how this channel fits existing payment operations without disproportionate cost or complexity
How Crypto Payments Work For Your Business
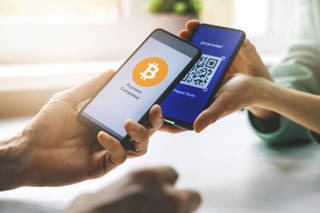
If you are researching how to accept crypto payments, start with the payment flow and the settlement outcome. A customer selects a supported asset, the payment system provides the required payment details, then the transaction is confirmed before funds reach your business account. A crypto payment processor can manage this workflow, with options for retaining assets or converting proceeds into fiat currency.
For businesses assessing crypto payments with B2BinPay, the provider currently lists merchant payment processing across several supported currencies, with immediate crypto settlement and T+1 fiat settlement, subject to onboarding and compliance review. Processing rates are tiered by monthly volume, from 0.40% for monthly incoming volume below $1 million to 0.25% for volume above $5 million. Separate minimum network charges apply, so the full cost depends on your transaction pattern. Service availability varies by jurisdiction.
What Crypto Payment Gateway Fees Really Include
Crypto payment gateway fees need to be assessed as a complete transaction cost, as the headline percentage is only one component. Your effective cost can include processor charges, network fees, currency conversion and banking costs, with the final figure also affected by settlement choices. If you convert receipts promptly into dollars, your exposure can differ from a business that retains digital assets for longer.
When you compare providers, ask how to accept crypto payments at your expected transaction volume, then model several realistic payment sizes. Many providers list separate rates for crypto and fiat settlement, as well as minimum commissions on some networks, so compare your expected transaction patterns against each published fee schedule.
Assessing The Risks Before You Accept Crypto Payments
Crypto payments for business carry financial and operational risks that deserve explicit controls. Asset prices can move significantly between receipt and conversion, and payments sent to the wrong address are often irreversible, so both require explicit controls. You also need controls for account access, transaction approvals, fraud monitoring and vendor dependency. Stablecoins can reduce direct price volatility, but they still involve issuer, liquidity, regulatory and operational considerations.
Regulation of payment stablecoins is also developing, with more jurisdictions introducing defined frameworks for issuers and service providers. Your assessment should cover the specific asset, provider and settlement route you intend to use, along with the rules that apply where your business and customers are based.
Tax And Accounting Requirements
If you want to accept crypto payments, design your accounting process before launch. Tax treatment of digital-asset receipts varies by jurisdiction, so confirm with a tax adviser how income, gains and losses should be measured and reported. Your records should capture the asset, timing, value in your reporting currency and relevant costs. Reconciliation can then connect invoices, receipts, conversions and accounting records.
How To Start With A Controlled Pilot
You can start small by defining which customers, assets and transactions qualify for the new payment option. Then decide when receipts will be converted, who can approve withdrawals and how exceptions will be handled. Your launch checklist should cover:
- Choose supported assets and settlement currency.
- Calculate crypto payment gateway fees at your expected volume.
- Establish wallet and account-access controls.
- Document transaction reconciliation procedures.
- Confirm tax and reporting obligations in your jurisdiction.
- Test refunds, failed payments and customer support.
Once these controls are established, a crypto payment processor can support a dedicated checkout flow or payment integration. Track transaction costs, settlement timing and reconciliation effort during the pilot, then use those results to decide whether wider adoption makes sense.
A Practical Approach To Crypto Payments
For small companies, crypto payments for business are best assessed as one component of a wider payment strategy. Compare the total processing cost with existing methods, measure customer demand and model the effect of conversion timing on cash management. Review provider terms regularly as fees, assets and rules can change.
The practical takeaway is straightforward: start with a defined use case, limited transaction scope and measurable controls. If the pilot shows that customers value the option while costs and operational workload remain manageable, you have evidence for a broader rollout. If the numbers do not support expansion, you have also limited the exposure created during the test.