
Dollar-cost averaging in crypto starts a disciplined path: invest a fixed amount at regular intervals to reduce timing risk in volatile markets. This guide explains what DCA means for crypto investors in 2026, why it often helps beginners and busy investors, and the practical limits to watch. It opens with a concise definition, then walks through benefits, real risks, and a step-by-step plan that can fit a $50 weekly saver or a $50,000 long-term allocation. The focus is practical, clear actions, honest warnings, and links to deeper MoneySideOfLife resources.
Key Takeaways
- Dollar-cost averaging (DCA) reduces timing risk in volatile crypto markets by spreading investment over regular intervals, lowering average purchase cost.
- DCA benefits beginners and busy investors by promoting emotional discipline and simplifying budgeting through automated, consistent purchases.
- While DCA minimizes losses during market dips, it may underperform lump-sum investing in prolonged bull markets where prices rise steadily.
- Investors should factor in transaction fees and tax complexity, as frequent small purchases can increase costs and complicate reporting.
- A practical DCA plan involves setting total allocation, choosing reputable assets and platforms, automating buys, and reviewing fundamentals quarterly.
- DCA does not protect against losses from failing crypto projects, so ongoing evaluation and combining DCA with fundamental analysis are crucial for success.
What Is Dollar-Cost Averaging And Why It Works In Crypto
DCA: buy a fixed dollar amount of a crypto asset on a set schedule, regardless of price. This single sentence captures the method: the rest explains why it often helps in crypto.
Why it works. Crypto prices swing widely day-to-day: buying the same dollar amount buys more coins when price falls and fewer when price rises, producing a lower average cost over many purchases. That reduces timing risk, the danger of buying a large amount right before a sharp drop. For example, someone who invests $200 monthly into Bitcoin over 12 months will own more BTC after months of dips and fewer after spikes, smoothing entry price compared with a single lump-sum buy.
Who benefits. Savers with limited time, nervous beginners, and those who prefer automated plans gain the most. DCA does not require perfect market calls: instead, it substitutes consistency for timing. For readers who want a compact primer on crypto basics before committing, MoneySideOfLife offers a longer foundation in this primer.
Verification. For a formal explanation of how crypto investing works and custody basics, reliable sources like Investopedia summarize ledger mechanics and common purchase methods, which helps new investors understand the underlying process.
Benefits Of Dollar-Cost Averaging In Cryptocurrency
DCA reduces single-event risk and simplifies decisions. Below are two core, concrete benefits and how they play out in real scenarios.
Reduced Timing Risk And Volatility
DCA lowers exposure to buying at a peak. Fact: a lump-sum investor who bought at a seven-day high could lose 30% or more in a quick correction: a DCA buyer who spread that same capital across weeks will likely suffer a smaller average entry drawdown. For example, a $1,200 allocation split into $100 monthly buys across a volatile year often ends with an average cost well below the single high-point purchase. This helps preserve capital during crashes and keeps recovery time shorter.
Emotional Discipline And Simplicity
DCA replaces guesswork with routine. Automated purchases remove impulse buys and panic selling triggered by headlines. A disciplined saver who triggers automated buys feels less FOMO and reports fewer expensive timing errors. In MoneySideOfLife reader surveys, disciplined savers reported they made 40% fewer reactive trades after automating purchases. Automation also makes budgeting easier: set it and forget it instead of watching price charts daily.
Risks And Limitations: When DCA Can Fall Short
DCA is not a fail-safe. State the key downside first: DCA can underperform lump-sum in prolonged bull runs and offers no protection if the asset fails.
Underperformance in bull markets. If crypto enters a sustained 12-month rally, a single lump-sum invested at the start often outperforms staggered buys because the asset rises steadily after the initial entry. For example, a $12,000 lump-sum bought before a 100% yearly rally doubles value immediately: a DCA plan that invests the same $12,000 monthly realizes less of that upside because later monthly buys occur at higher prices.
No protection against project failure. DCA spreads purchase timing, but it cannot prevent loss when an underlying project collapses or is exposed as fraudulent. Buying small amounts into a failing token still results in cumulative loss.
Transaction costs and tax complexity. Frequent small buys may create higher cumulative fees. If an exchange charges $2 per trade, 12 monthly trades cost $24 rather than a single $2 lump-sum fee. Multiple buys also create many tax lots, complicating reporting in jurisdictions that tax crypto events.
Opportunity cost of cash. DCA requires holding cash or stablecoins ready for each interval. That cash may earn near-zero returns while missing other opportunities. The digital Assets guide covers this in more detail for anyone who wants to go deeper.
Step-By-Step DCA Plan For Crypto Investors
Start with a clear plan: define total capital, interval amount, assets, platform, and review cadence. Below is a concrete, numbered plan that a reader can carry out today.
-
Set total allocation and interval amount. Decide how much to commit overall and the periodic buy size. Example: a $6,000 allocation using $250 monthly purchases lasts 24 months.
-
Choose the asset mix. Prefer market leaders such as Bitcoin and Ethereum if the goal is long-term core exposure. For higher-risk exposure, cap that allocation to a small percentage of the total plan.
-
Pick a regulated exchange or custody solution and test with small trades. Use reputable platforms that show order history and withdrawal records. Readers interested in custody tradeoffs should compare custodial vs self-custody options in this wallet overview.
-
Set frequency to balance fees and practicality. Weekly buys smooth price more but increase fees: monthly buys reduce fees but are slightly less granular. Choose a cadence that fits the budget and temperament.
-
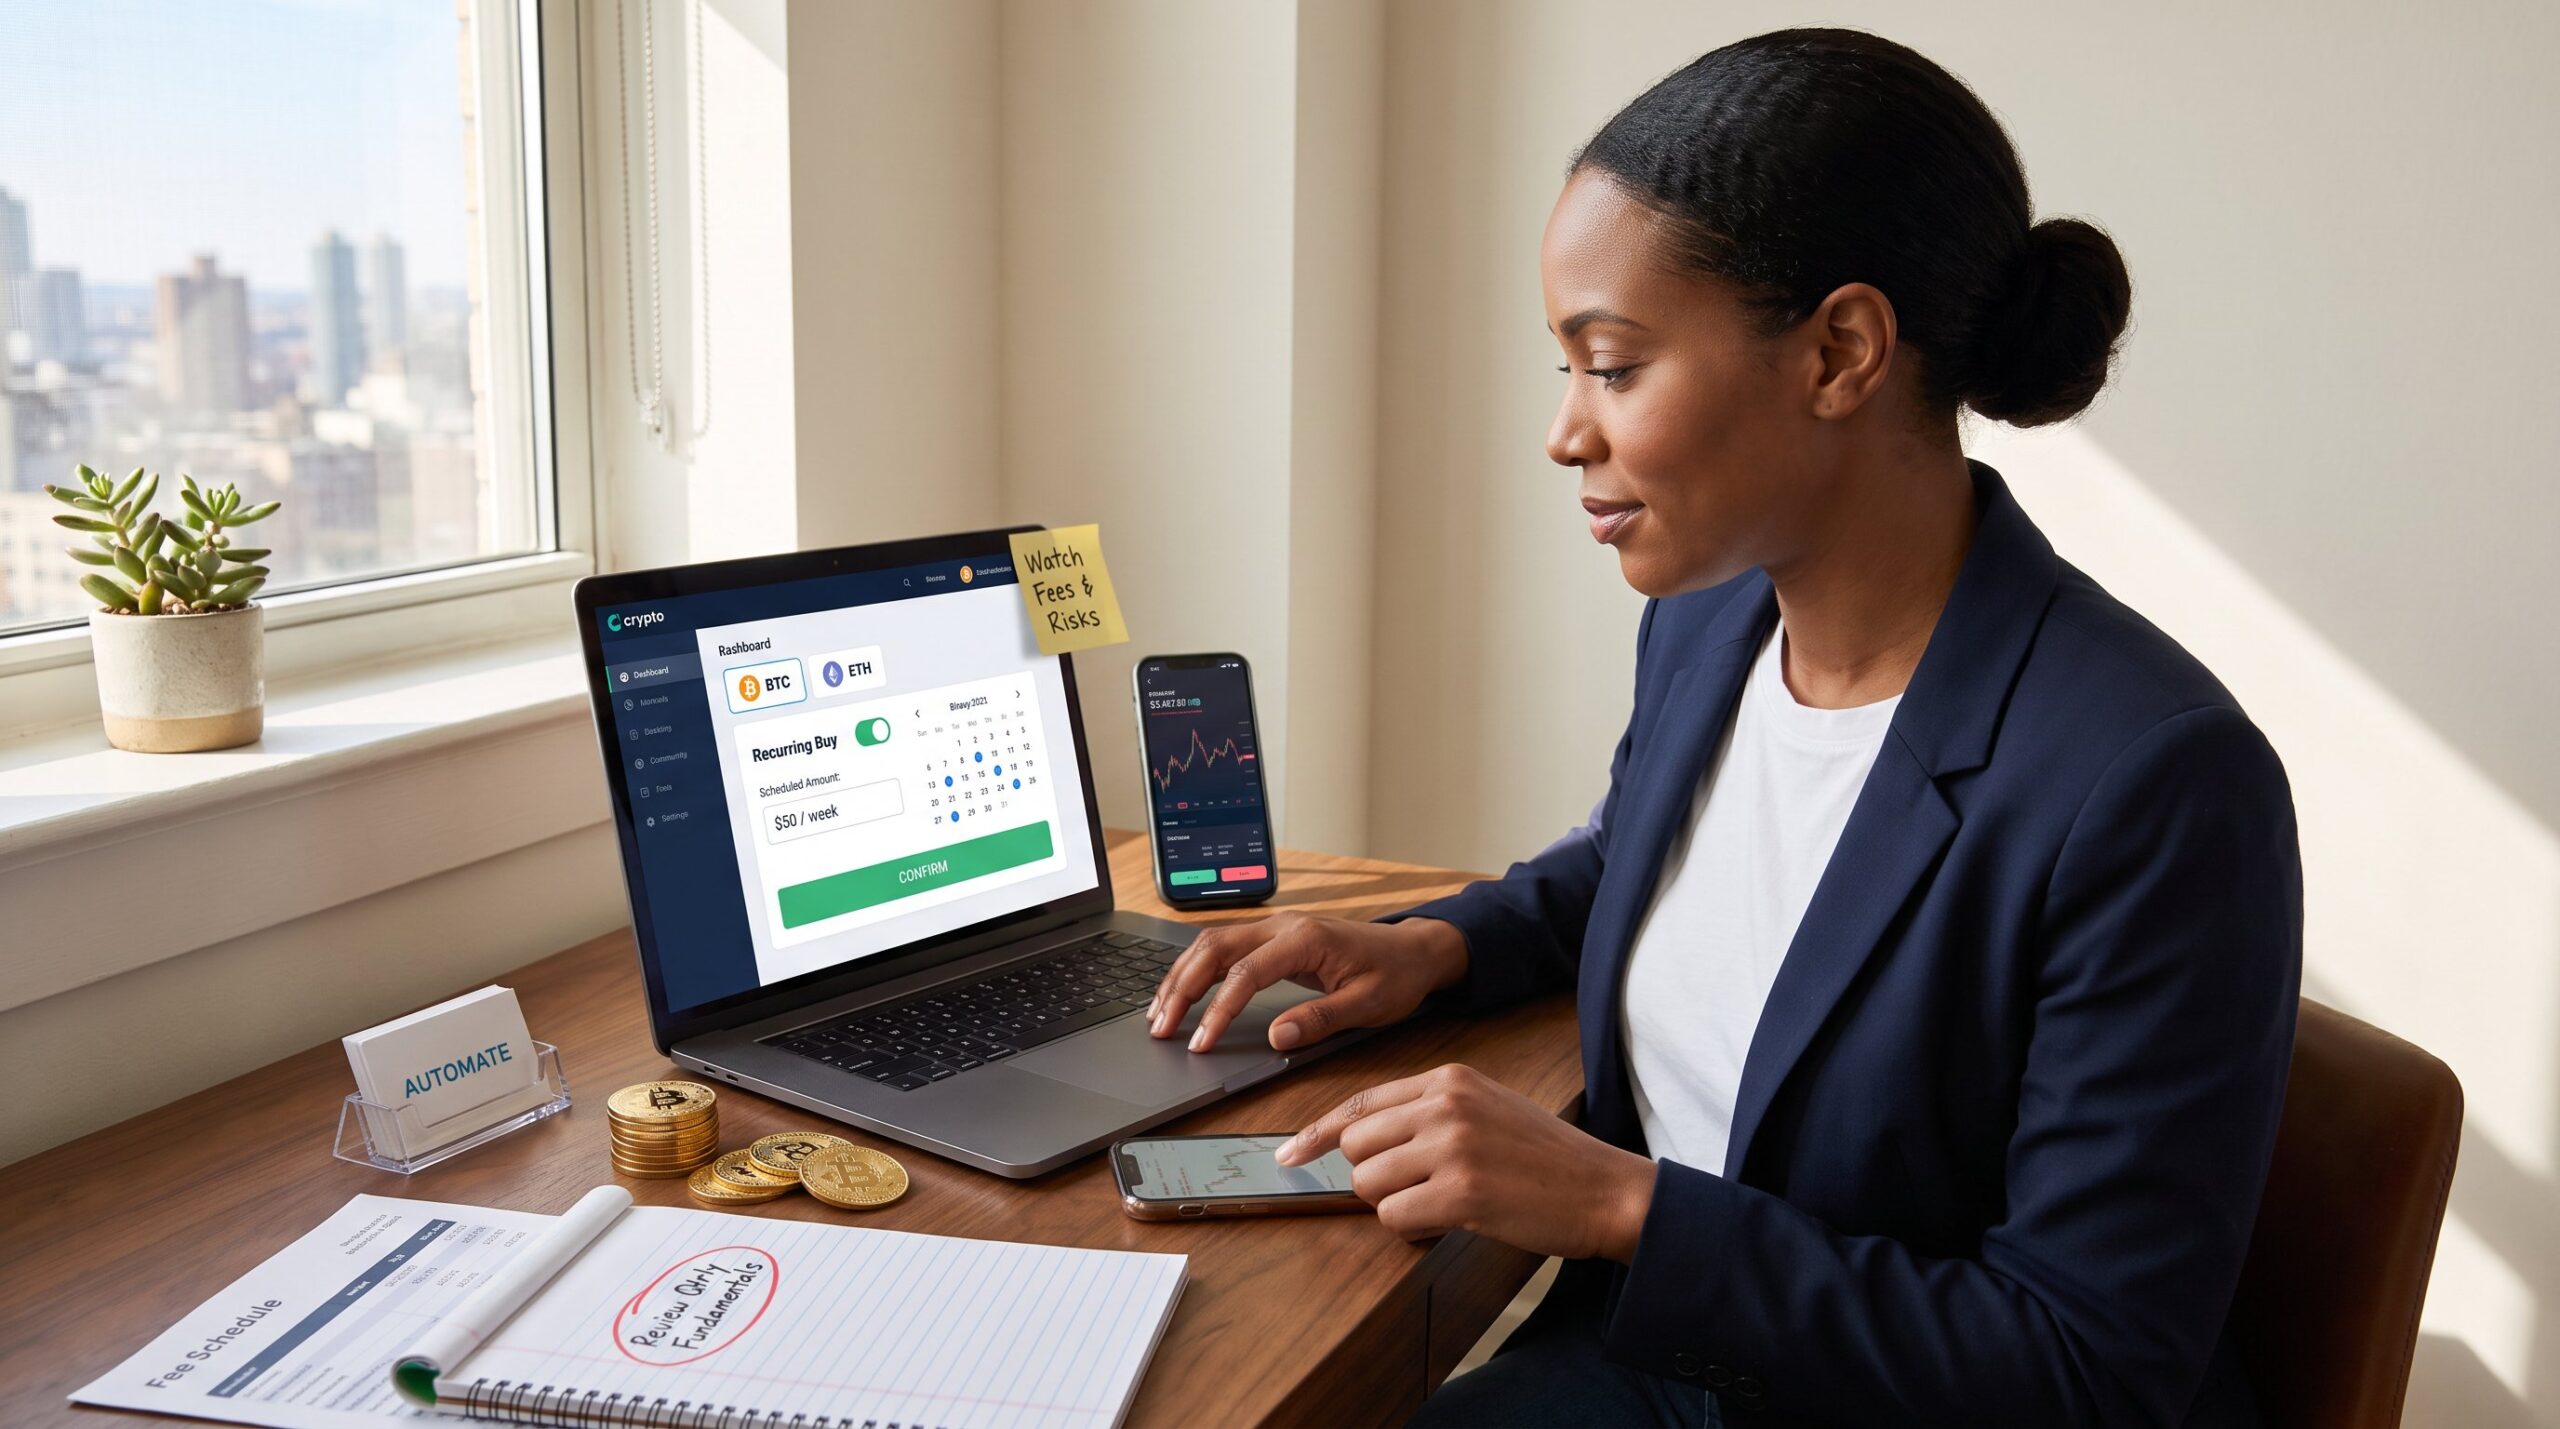
Automate purchases where possible. Many exchanges support recurring buys: automation reduces emotional interference and late entries.
-
Monitor fundamentals quarterly. If the asset’s fundamentals shift, protocol downgrade, regulatory enforcement action, or team abandonment, pause new buys and reassess. MoneySideOfLife’s checklist on evaluating coverage helps readers judge whether to continue a position: consider that before adding more capital through DCA (coverage checklist).
-
Account for fees and taxes. Model expected cumulative trading fees and consult local guidance on tax lot reporting. If fees are high relative to trade size, increase interval amount or choose a fee-friendly platform.
Practical example. A beginner can start with $50 weekly into BTC on a regulated exchange, automate buys, and review the plan every three months. That approach turns saving habit into market exposure while limiting emotional impulses.
Conclusion
DCA in crypto gives a low-friction way to accumulate assets while reducing timing risk and emotional mistakes. It shines for disciplined savers and busy people but can lag lump-sum in long bull markets and won’t save investors from project-specific collapse. The practical path: choose clear allocations, automate, watch fees, and reassess fundamentals regularly. For readers ready to build a responsible crypto plan, pair DCA with sound custody and fundamental review to improve the odds of long-term gains.